Tell Your Mortgage Professional Everything: The Small Financial Details That Can Become Big Problems Later
When you’re applying for a mortgage, there is one piece of advice I wish every home buyer knew from the very beginning:
Tell your mortgage professional everything.
Especially the things you think don’t matter.
A financial gift from your parents several months ago.
A new payment arrangement.
A property you own with someone else.
A debt you’re responsible for that doesn’t appear on your credit report.
Money recently transferred between accounts.
A new job, raise, bonus, side business, or change in compensation.
An upcoming large purchase.
A change in marital status.
Another property you plan to sell.
Even something that happened months before you decided to buy a home.

You may look at one of these situations and think:
“That has nothing to do with my mortgage.”
Maybe.
But let your mortgage professional make that determination.
If you’re buying a home in Port St. Lucie, Royal Palm Beach, Wellington, Tequesta, Jupiter, Tampa, or anywhere in Florida, one of the easiest ways to protect your mortgage process is simply to communicate early and completely.
Your Mortgage Professional Needs the Whole Story
Mortgage underwriting is not based on one number.
It is not simply your credit score.
It is not simply your income.
And it is not simply the amount you have in your bank account.
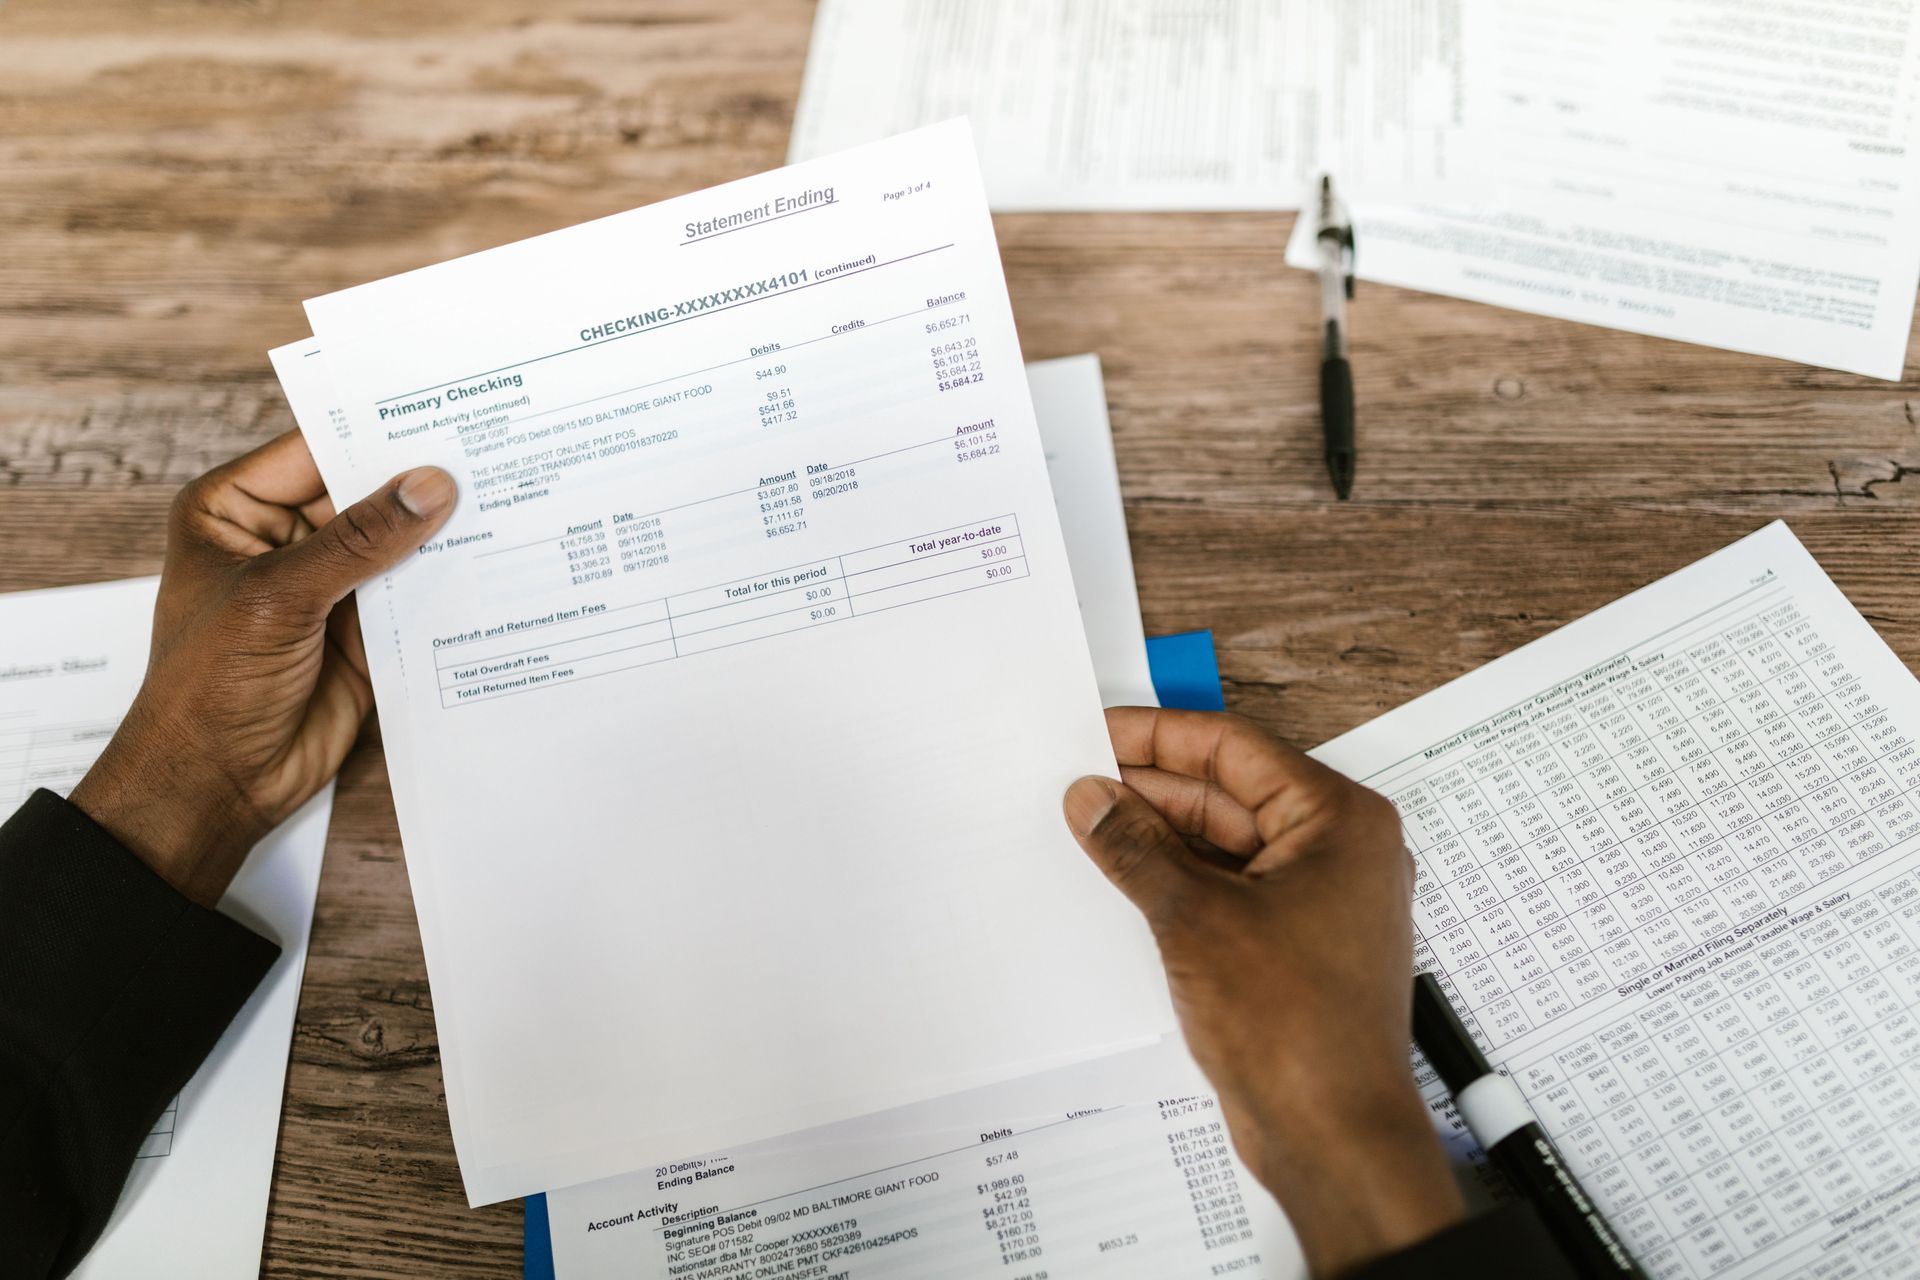
Your mortgage application brings together your income, assets, debts, employment, credit history, property, occupancy and many other pieces of your financial picture.
Fannie Mae specifically notes that lenders may require documentation covering income, checking and savings accounts, investments, gift funds and other financial information. Freddie Mac guidelines also contain requirements for evaluating certain deposits and borrowed funds. (Fannie Mae)
Something that seems insignificant to you could create a question for an underwriter.
The sooner we know about it, the sooner we can determine whether it matters and, when necessary, document it properly.
That Gift From Months Ago Could Still Matter
Imagine this.
Your parents gave you money several months ago.
At the time, you weren’t even seriously shopping for a home.
Now you’re ready to purchase.
The money is sitting in your bank account, so you don’t think to mention it.
Depending on when the funds were deposited, what account documentation is required, whether those funds are needed for the transaction and the applicable loan guidelines, the deposit could potentially require additional review.
Freddie Mac, for example, has specific requirements concerning certain large deposits needed to qualify a borrower, and its guidelines separately address documentation for gift funds. (Freddie Mac Guide)
That doesn’t automatically mean there is a problem.
It means we should know about it.
Tell us before we have to discover it.
Don’t Decide What Is Important for the Underwriter
This may be the most important lesson in this article.
You don’t need to understand mortgage underwriting.
That’s our job.
Your job is simply to give us an accurate picture.
I’ve seen buyers avoid mentioning something because they genuinely believed it wasn’t relevant.
That can create unnecessary questions later.
A much better conversation is:
“Edgar, I don’t know if this matters, but I want you to know about it.”
Perfect.
Tell me.
If it doesn’t matter, great.
If it does matter, we have more time to address it.
Undisclosed Debt Can Change Qualification
The same principle applies to debt.
If you are responsible for an obligation that doesn’t appear where you expect it to, tell your mortgage professional.
Fannie Mae’s current guidance states that if additional liabilities are disclosed or discovered after underwriting, including up to closing, the lender may need to recalculate the borrower’s debt to income ratio. (Fannie Mae Selling Guide)
That could potentially affect qualification.
Finding out early gives everyone more opportunity to evaluate the situation correctly.
Finding out days before closing is a very different experience.
Your Financial Life Should Become Boring During the Mortgage Process
Once you’re preparing to buy a home, boring can be beautiful.
Avoid making significant financial changes without first discussing them with your mortgage professional.
Before you:
Open new credit.
Finance furniture.
Buy or lease a vehicle.
Move large amounts of money.
Change jobs.
Change how you’re paid.
Co sign for someone.
Accept significant funds from another person.
Pay off a major debt.
Make an unusually large purchase.
Call first.
A five minute conversation today could prevent days of additional documentation tomorrow.
Never Be Embarrassed to Tell Us Something
This matters to me.
Your mortgage professional isn’t there to judge your financial history.
We’re there to understand it.
Maybe your credit isn’t perfect.
Maybe a family member helped you.
Maybe you made a financial decision you regret.
Maybe your income changed.
Maybe something happened that you don’t think looks good on paper.
Tell us anyway.
Sometimes there is an easy explanation.
Sometimes documentation solves the issue.
Sometimes we need a different mortgage strategy.
And sometimes we may need more time before you’re ready.
But we cannot help solve something we don’t know exists.
Surprises Are Wonderful at Birthdays. Not at Underwriting.
Mortgage professionals expect questions.
Underwriters ask questions.
Documents sometimes lead to additional documents.
That’s normal.
What we want to avoid are preventable surprises late in the transaction.
The earlier you communicate, the more opportunity your mortgage team has to prepare.
That is why one of my simplest pieces of advice for every home buyer is also one of my most important:
When in doubt, disclose it and ask.
Your Next Step
If you’re thinking about buying a home in Port St. Lucie, Royal Palm Beach, Wellington, Tequesta, Jupiter, Tampa, or anywhere in Florida, don’t worry about knowing what information matters before calling me.
That’s what I’m here for.
Tell me your complete story.
Ask every question.
Mention the things you think probably don’t matter.
My job isn’t simply to help you obtain a mortgage.
My commitment is to understand your situation, explain the process clearly, anticipate potential challenges whenever possible and help you make informed decisions from your first conversation through closing.
The strongest mortgage application isn’t the one with no questions.
It’s the one we understand.
Contact Information
Edgar DeJesus
NMLS #230414
Call or Text: 561-223-9347
Email: Edgar@TreasureCoastHomeLoans.com
Helping home buyers throughout Port St. Lucie, Royal Palm Beach, Wellington, Tequesta, Jupiter, Tampa, and communities across Florida navigate the mortgage process with greater clarity and confidence.
Important Disclosure
This article is provided for educational and informational purposes only and does not constitute legal, tax, financial or lending advice. Mortgage documentation and underwriting requirements vary based on the borrower, loan program, lender, property, transaction and applicable guidelines.
Loan approval is not guaranteed and is subject to verification and lender review of all information provided. All approvals are conditional and subject to satisfaction of applicable lender and program requirements. Borrowers should provide complete and accurate information and promptly communicate material changes that occur during the mortgage process.
Interest rates, annual percentage rates, loan programs, lender credits, discount points, closing costs, underwriting guidelines and program availability are subject to change without notice and may vary based on borrower qualifications and market conditions.
Innovative Mortgage Services, Inc. is a Florida licensed lender.
Company NMLS #250769
Originator NMLS #230414
Florida Mortgage Lender License #MLD178
Florida Mortgage Lender Servicer License #MLD2167
Equal Housing Lender
Call or text 561-223-9347 or email edgar@treasurecoasthomeloans.com to discuss your loan.
Loan approval is not guaranteed and is subject to lender review of information. All loan approvals are conditional and all conditions must be met by the borrower(s). A loan is only approved when the lender has issued approval in writing and is subject to all lender conditions. Any specified rates and terms are contingent upon loan approval and are subject to change without notice due to unpredictable market conditions. Innovative Mortgage Services, Inc. is a Florida licensed lender. Company NMLS #250769. Originator NMLS # 230414. Florida Mortgage Lender License, License/Registration #: MLD178 Florida. Mortgage Lender Servicer License, License/Registration #: MLD2167 Equal. Equal Housing Lender
Mortgage Broker Port St. Lucie, Florida
Learn More About the Mortgage Process.
Check Out Our Google Verified Reviews
Everyone Says Homes Are Unaffordable. What If You Shopped the Entire Homeownership Equation Instead?